School Accounting Solutions
See what you’ve been missing.
Payment & Fee Management
Track Every School Payment.
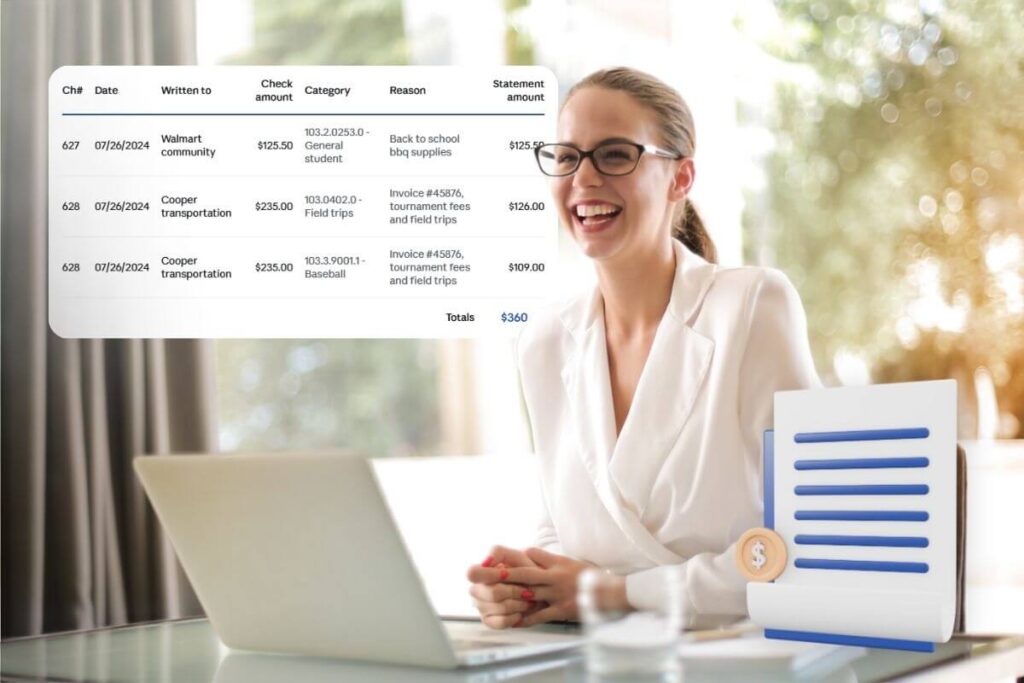
School Disbursement Solutions
Accountability for every dollar out.
School Facility Management
Keep every school facility operate safely.
There’s a paradox in K-12 finance
See the surprising new research from a survey of nearly 1000 district finance leaders, school staff, and parents.
 What It Really Costs to Keep Money Moving: Insights from K-12
Discover what the research reveals about the hidden time, money, and risk of managing school activity funds.
An activity fund is a pool of money a school maintains separately from its general operating budget to support student-driven activities such as clubs, athletics, field trips, and fundraisers. Unlike tax-levied general funds, activity fund dollars typically originate from student and community sources, including ticket sales, membership dues, and vendor fundraising, which is part of why they are governed by their own accounting rules rather than the district’s core chart of accounts.
Because activity funds involve cash collected by teachers, coaches, and club advisors rather than centralized finance staff, they carry a distinct risk profile. Multiple people handle deposits, receipts get written by hand, and reconciliation often lags behind the pace of collections. Auditors consistently flag activity funds as a source of control weaknesses because the same person who collects the money is often the one who records and deposits it, violating basic separation-of-duties principles.
Strong activity fund governance requires standardized deposit procedures, advisor training, and regular account reconciliation, ideally supported by software rather than spreadsheets or cabinets of receipts. KEV Group’s guidance on student activity fund management and its companion piece on activity fund best practices outline the controls districts use to keep these funds audit-ready year-round rather than scrambling each spring.
An audit deficiency is a finding by external or internal auditors that a school district’s internal controls, financial records, or compliance processes fall short of what sound financial management requires. Deficiencies range in severity from minor clerical issues to significant control gaps, and each one gets classified according to how much risk it poses to the accuracy of the district’s financial statements.
For a business office, deficiencies are rarely one-time surprises. They tend to recur in the same areas year after year: activity fund reconciliation, purchase order approval trails, payroll segregation of duties, and inventory of fixed assets. Auditors look for evidence that a control operated consistently throughout the year, not just at the moment of testing, which is why districts that rely on manual, ad hoc processes are disproportionately represented in deficiency findings.
The practical fix is building repeatable, documented controls into daily finance operations rather than treating compliance as an annual scramble. KEV Group’s analysis of why K-12 school districts fail audits breaks down the most common deficiency categories, and the accompanying audit preparation checklist gives business administrators a working framework for closing gaps before fieldwork begins.
Audit failure describes an outcome where a school district’s financial statements or internal controls are found materially inadequate during an external audit, typically resulting in a qualified opinion, an adverse opinion, or a disclaimer rather than the clean, unmodified auditor opinion districts aim for. It is the escalation point past ordinary findings: a pattern of unresolved deficiencies or a single serious control breakdown that undermines confidence in the numbers.
The consequences extend well beyond the audit report itself. A failed audit can trigger increased state oversight, jeopardize bond ratings and borrowing costs, invite additional scrutiny from the school board and community, and in some cases put federal or state funding at risk if compliance requirements tied to that funding were not met. For a CFO or business administrator, the reputational cost with the board and superintendent is often more immediate than any of the formal consequences.
Most audit failures trace back to the same root causes: fragmented systems, manual reconciliation, and thin segregation of duties across a small business office team. KEV Group’s breakdown of why K-12 school districts fail audits walks through these patterns in detail and how districts can address them before they compound into a failed audit.
Bank reconciliation is the process of comparing a school district’s internal cash records, whether a general ledger account, an activity fund ledger, or a site-level cash log, against the corresponding bank statement to confirm the two agree, and to identify and resolve any differences such as outstanding checks, deposits in transit, or bank fees not yet recorded internally. It is the most basic control a business office or bookkeeper performs to confirm that recorded cash actually exists.
In a school setting, bank reconciliation gets complicated by the number of accounts involved. A mid-size district might reconcile a general operating account, a payroll account, a debt service account, and dozens of individual school-level activity fund accounts every month, each requiring its own reconciliation. When this workload falls behind, discrepancies compound quietly for months, and what should have been a five-minute fix becomes a multi-week forensic exercise once auditors or a new bookkeeper eventually catch it.
A monthly, non-negotiable reconciliation cadence, ideally supported by software that flags mismatches automatically, is one of the most effective controls a business office can implement. KEV Group’s guide to strengthening school finance controls walks through how districts build reconciliation into a routine rather than an annual scramble.
A cashless school is one that has moved student and parent payments, such as lunch money, field trip fees, and activity dues, away from physical cash and checks and onto digital payment channels. Rather than students carrying cash to the front office or handing bills to a teacher, parents pay online or through a mobile app, and the funds post directly to the appropriate school or district account.
The shift to cashless operations is driven as much by risk reduction as by convenience. Physical cash handling multiplies the number of people who touch money between collection and deposit, each an opportunity for loss, error, or theft, and it consumes staff time that could go toward instructional support instead of counting bills and reconciling envelopes. Cashless payment systems also generate a digital audit trail automatically, which materially reduces the reconciliation burden discussed under Reconciliation and helps address the control gaps auditors flag under Audit Deficiency.
Districts moving toward cashless operations typically start with the highest-volume payment categories, like school fees and lunch accounts, before expanding to activity funds and fundraisers. KEV Group’s guide to online payments for schools covers how districts sequence that rollout and what to look for in a payment processor built specifically for K-12 finance offices.
A disbursement is any payment a school or district makes out of its accounts, whether by check, electronic transfer, or purchasing card, to cover expenses such as vendor invoices, payroll, reimbursements, or activity fund purchases. It is the counterpart to a deposit, and every disbursement should trace back to an approved purchase order or authorization before the payment is released.
Disbursement controls are a frequent audit focus because this is the point where money actually leaves the district, making it the highest-risk step in the purchasing cycle. Auditors specifically test whether disbursements were properly authorized before payment, whether supporting documentation like invoices and receiving reports exists, and whether the person approving a disbursement is different from the person who requested or received the goods. This is the separation-of-duties principle that appears throughout school finance control frameworks.
Clear disbursement policies, including dollar thresholds that require additional sign-off, are a standard recommendation in most district financial control frameworks. KEV Group’s guidance on strengthening school finance controls covers where disbursement approval typically breaks down and how to tighten it.
An ERP, or enterprise resource planning system, is the central software platform a school district uses to manage core financial operations such as general ledger accounting, budgeting, purchasing, payroll, and human resources. In K-12, the ERP is typically the system of record that state and federal reporting, board financial statements, and external audits all trace back to.
K-12 finance teams face a specific challenge that private-sector ERP buyers usually don’t: the ERP has to coexist with a constellation of specialized systems, including student information systems (SIS), activity fund and cashless payment platforms, facilities and asset management tools, and fundraising software. Without deliberate integration, each of these systems becomes its own island of data, forcing staff to manually re-enter information and reconcile numbers across platforms by hand, which is exactly the kind of manual process that produces audit deficiencies.
The strategic question for most districts isn’t whether to have an ERP, but how well it connects to everything else in the finance and operations stack. KEV Group’s solution overview and its list of integrations outline how fund accounting, payments, and facilities data can flow into and out of a district’s core ERP rather than living in silos.
A financial emergency, sometimes called fiscal distress, is a formally recognized state in which a school district’s finances have deteriorated to the point that it can no longer meet its obligations without state intervention. Most states define specific triggers, such as a projected deficit exceeding a set percentage of the operating budget, failure to make payroll or debt payments, or repeated qualified audit opinions, that automatically move a district into this status.
Once a district is declared to be in financial emergency, local control over spending decisions is typically curtailed. States commonly appoint a fiscal oversight commission, a state-appointed fiscal officer, or in extreme cases a full state takeover of financial decision-making, stripping the elected board and superintendent of budget authority until the district demonstrates it can operate within a state-approved recovery plan. That loss of local control, more than the underlying dollar figures, is usually what business administrators and boards are trying hardest to avoid.
Districts rarely arrive at financial emergency status overnight; it is usually the endpoint of years of underlying structural issues, like declining enrollment, cost growth outpacing revenue, and weak forecasting visibility. KEV Group’s look at the K-12 school finance blind spot examines the early warning signs finance teams often miss until a shortfall is already unmanageable.
Fiscal emergency is used interchangeably with financial emergency in most state statutes, referring to the legally defined status a school district enters when specific financial distress indicators are triggered, such as an inability to meet payroll, a deficit fund balance, or a pattern of adverse audit findings. The exact terminology and thresholds vary by state, with some using ‘fiscal watch’ or ‘fiscal caution’ as earlier-stage designations before a full fiscal emergency is declared.
What distinguishes fiscal emergency from ordinary budget tightening is the external response it triggers. Rather than the district managing its own recovery, a state agency, oversight commission, or appointed fiscal supervisor typically takes on approval authority over the budget, contracts, and sometimes staffing decisions until the district exits the designation. For a CFO or treasurer, operating under a fiscal emergency designation means every significant financial decision runs through an additional layer of state-level sign-off.
Because the designation is triggered by measurable indicators, districts can track their own risk exposure well before a state agency does. KEV Group’s discussion of the K-12 school finance blind spot covers the forecasting and visibility gaps that most commonly precede a fiscal emergency declaration.
GASB, the Governmental Accounting Standards Board, is the independent organization that establishes accounting and financial reporting standards for U.S. state and local governments, including public school districts. When a district’s financial statements are described as prepared ‘in accordance with GAAP,’ for a government entity that
specifically means GASB standards, not the standards that apply to private companies or nonprofits.
GASB standards directly shape how districts report fund balances, pensions, other post-employment benefits (OPEB), and capital assets, among many other areas, and updates to these standards periodically require districts to change how they classify or disclose specific items. Because external auditors test compliance with GASB requirements as part of every audit, a district’s chart of accounts and reporting templates need to stay current with the latest GASB statements or risk generating findings tied to reporting deficiencies rather than actual financial mismanagement.
Fund accounting software built specifically for government and education entities is typically designed around current GASB reporting requirements, unlike general-purpose accounting tools. KEV Group’s coverage of why K-12 school districts fail audits touches on how reporting-standard gaps show up in audit findings.
A hold harmless provision, in the context of school funding, is a clause built into state or federal funding formulas that guarantees a district will not receive less funding than it did in a prior year, even if a formula change, an enrollment drop, or a policy update would otherwise reduce its allocation. It functions as a floor under a district’s revenue rather than a permanent guarantee of growth.
These provisions matter enormously to district financial planning because they are almost always temporary. A hold harmless clause frequently phases out over a set number of years, meaning a district that has come to rely on protected funding levels can face a real budget cliff once the provision expires, even without any change in enrollment or local circumstances. Business administrators tracking multi-year budget projections need to flag which revenue lines are protected by hold harmless language and which will revert to formula-driven amounts on a known future date.
Funding cliffs tied to expiring hold harmless provisions are exactly the kind of forward-looking risk that catches districts by surprise when forecasting visibility is weak. KEV Group’s discussion of the K-12 school finance blind spot covers how districts build visibility into revenue changes like these before they hit the budget.
Internal controls are the policies, procedures, and system safeguards a school district puts in place to ensure financial transactions are authorized, accurately recorded, and protected against error or misuse. They span everything from requiring two signatures on large checks, to separating who requests a purchase from who approves it, to restricting who can edit a posted journal entry.
The strength of a district’s internal controls is essentially what an external audit is testing, more than the raw numbers themselves. Auditors evaluate whether controls are properly designed and, just as importantly, whether they actually operated consistently throughout the year rather than existing only on paper. Weak internal controls are the underlying cause behind most Audit Deficiency and Material Weakness findings, and they are also the primary defense against Misappropriation of School Funds, since a well-designed control removes the unchecked opportunity that most fraud depends on.
Building internal controls that hold up under audit testing, not just controls that look
good in a policy manual, requires consistent, system-enforced processes. KEV Group’s strengthening school finance controls and its fraud risk reduction guide both walk through the specific controls districts implement.
A journal entry is a record in a district’s general ledger that documents a financial transaction, specifying which accounts are debited and which are credited so the books stay in balance. Most day-to-day transactions, like a vendor payment or a payroll run, post automatically as journal entries generated by the underlying finance system, but bookkeepers and accountants also make manual journal entries to correct errors, record depreciation, allocate shared costs across funds, or record transactions that don’t flow through a standard subsystem.
Manual journal entries receive outsized attention from auditors precisely because they bypass the automated controls built into routine transaction processing. An entry created directly in the general ledger, without a purchase order, invoice, or receipt behind it, is one of the easiest ways for an error or an unauthorized adjustment to enter the books unnoticed, which is why most district policies require manual journal entries to be reviewed and approved by someone other than the person who created them.
Fund accounting software that logs every journal entry with a full audit trail, including who created and approved it, closes much of this exposure automatically. KEV Group’s solution overview covers how transaction-level controls are built into its fund accounting platform.
A Key Performance Indicator, or KPI, is a specific, measurable data point a district’s business office tracks over time to gauge financial health or operational performance, such as the ratio of unrestricted fund balance to operating expenditures, days of cash on hand, or the percentage of activity fund accounts reconciled on schedule each month. KPIs turn broad goals like ‘stay financially healthy’ into numbers that can actually be monitored and reported to a board.
The value of finance KPIs in a school district comes from consistency and trend visibility rather than any single data point in isolation. A fund balance ratio that looks acceptable in isolation can mask a multi-year downward trend that, left unaddressed, eventually contributes to the kind of Financial Emergency designation districts work hard to avoid. Boards and superintendents increasingly expect CFOs to present a small, consistent dashboard of these indicators at every meeting rather than a raw financial statement alone.
Tracking the right KPIs depends on having timely, accurate underlying data rather than month-old spreadsheet exports. KEV Group’s look at the K-12 school finance blind spot discusses the visibility gaps that keep many districts from tracking meaningful financial KPIs in real time.
A line-item budget is a budgeting format that lists planned spending by specific category or object code, such as salaries, supplies, utilities, or travel, rather than by program or outcome. It is the traditional budgeting approach used by most school districts, largely because it aligns directly with the chart of accounts and makes it straightforward to track actual spending against a specific approved amount in each category.
The main criticism of line-item budgeting is that it shows what a district is spending money on without directly showing what it’s achieving with that spending, since a program can be fully funded across a dozen scattered line items with no single number representing its total cost. Many districts address this by supplementing their line-item budget with program-based or functional views for board and community communication, while keeping the underlying line-item structure for day-to-day financial control and compliance reporting.
Whichever budgeting philosophy a district favors, the underlying system still needs to support granular line-item control and reporting to satisfy state reporting requirements and auditor expectations. KEV Group’s school finance buyer’s guide covers what to look for in budgeting and reporting flexibility when evaluating finance software.
A material weakness is the most severe category of internal control deficiency an auditor can report, indicating a reasonable possibility that a material misstatement in the district’s financial statements would not be prevented or detected in a timely manner. It sits above a ‘significant deficiency,’ which is serious but less severe, and its presence in an audit report is a red flag that gets attention from the school board, the state department of education, and often the community and local press.
Material weaknesses tend to originate from structural gaps rather than isolated mistakes: irregular reconciliation of bank statements to the general ledger, a single staff member with unchecked authority over both purchasing and payment approval, or activity fund deposits that go unrecorded for months at a time. Because these are systemic issues, a material weakness identified in one year’s audit frequently reappears the following year if the underlying process isn’t redesigned.
Remediating a material weakness usually requires rebuilding the control itself, not just correcting the specific transaction that triggered the finding. KEV Group’s analysis of why K-12 school districts fail audits and its K-12 fraud report both examine the control gaps most likely to escalate into material weakness findings.
Misappropriation of school funds refers to the improper or unauthorized use of district or school-level money, ranging from outright theft to more subtle diversions such as an employee using a district purchasing card for personal expenses or an activity fund advisor spending club dues without authorization. It is distinct from an honest accounting error in that it involves a departure from the intended use of the funds, whether or not criminal intent is ultimately proven.
School districts are particularly exposed to misappropriation risk because so much of the cash handling happens outside the central business office, in classrooms, athletic departments, and front offices where a single person often collects, records, and deposits money with no independent check on their work. The ‘fraud triangle’ framework, pressure, opportunity, and rationalization, explains why these seemingly small opportunities compound over time into some of the largest losses documented in district fraud cases.
Preventing misappropriation comes down to closing the opportunity side of that equation through separation of duties, surprise reconciliations, and system-enforced approval workflows. KEV Group’s fraud triangle and activity fund fraud prevention piece, along with its K-12 fraud report, documents how these losses actually happen and what controls close the gap.
Net position is the government-accounting equivalent of net worth, representing the difference between a school district’s total assets plus deferred outflows and its total liabilities plus deferred inflows, as reported on the district-wide Statement of Net Position under GASB standards. It is reported in three components: net investment in capital assets, restricted net position, and unrestricted net position, each telling a different story about the district’s financial flexibility.
A district’s net position is one of the first figures a board member, bond rating agency, or state oversight body looks at to gauge overall financial trajectory, since it captures long-term obligations like pension liabilities and debt alongside short-term assets in a single figure. A declining net position over several consecutive years, even if the annual operating budget appears balanced, is often an early indicator of the kind of structural financial stress that can eventually lead to a Financial Emergency designation.
Because net position blends so many moving parts, from capital assets to long-term liabilities, tracking it accurately depends on clean underlying fund accounting data throughout the year, not just at close. KEV Group’s discussion of the K-12 school finance blind spot covers why so many districts only discover a net position problem after it has already become serious.
An operating budget is a school district’s financial plan for its day-to-day expenses over a fiscal year, covering salaries, benefits, instructional supplies, utilities, and routine maintenance, as distinct from capital budgets that fund longer-term investments like new construction or major equipment purchases. It is typically the largest and most closely watched fund in a district’s overall budget, and it is the one most directly tied to enrollment-driven state and local revenue.
Operating budgets are built and monitored throughout the year against actual spending, with business offices tracking variance in real time so that overspending in one category can be caught and addressed before it becomes a year-end crisis. Because roughly 80 percent or more of most district operating budgets goes toward personnel costs, even small percentage miscalculations in enrollment projections or staffing ratios can create outsized budget variances that ripple through the rest of the operating plan.
Keeping the operating budget aligned with real-time actuals rather than static annual projections is one of the clearest ways to avoid sudden budget surprises. KEV Group’s school finance buyer’s guide outlines what finance teams look for in budgeting and
forecasting tools that keep pace with actual spending.
A purchase order, or PO, is a formal document a school or district issues to a vendor authorizing a specific purchase, specifying the items or services, quantities, agreed price, and the budget line the expense will be charged against. POs are created and approved before the purchase happens, which distinguishes them from invoices, which the vendor sends after goods or services have been delivered.
The purchase order is the anchor point for most district spending controls: it confirms budget availability before money is committed, creates a paper trail an auditor can trace from request to approval to payment, and prevents staff from making unauthorized commitments the business office later has to honor without having budgeted for them. Auditors specifically test whether disbursements can be matched back to an approved purchase order, making a consistently followed PO process one of the more straightforward ways to avoid Audit Deficiency findings tied to purchasing.
A purchase order process that’s actually followed by school-level staff, not just written down as policy, depends heavily on how easy the system makes it to create and track POs. KEV Group’s solution overview covers how purchasing and approval workflows connect to the rest of the fund accounting platform.
A qualified opinion is a type of audit opinion an external auditor issues when a district’s financial statements are fairly presented overall, except for one or more specific issues the auditor identifies and describes in the report. It sits between an unmodified, or ‘clean,’ opinion, which every district aims for, and the more severe adverse opinion or disclaimer of opinion, which indicate much broader problems with the financial statements as a whole.
A qualified opinion typically results from a scope limitation, meaning the auditor couldn’t obtain enough evidence to test a specific area, or from a specific departure from GASB standards in how an item was accounted for, while the rest of the statements remain reliable. Even though it’s less severe than an adverse opinion, a qualified opinion still draws attention from the board, the state, and bond rating agencies, and it typically requires the district to explain, in writing, the specific issue and its remediation plan going forward.
Most qualified opinions trace back to the same documentation and control gaps that drive other audit findings, which is why prevention overlaps heavily with general audit readiness. KEV Group’s analysis of why K-12 school districts fail audits and its audit preparation checklist both address the issues most likely to trigger a qualified opinion.
Reconciliation, in a school finance context, is the process of comparing two independent sets of financial records, most commonly a bank statement against the general ledger, to confirm they agree and to identify and resolve any discrepancies. In a district’s day-to-day operations, reconciliation also applies at a smaller scale: matching activity fund deposit logs to bank deposits, or matching purchase orders to invoices and payments received.
Reconciliation is where most control weaknesses in K-12 finance become visible, because it is the step that catches errors, delays, or missing deposits before they compound. When reconciliation happens monthly and consistently, small discrepancies get caught and corrected quickly. When it happens quarterly, annually, or only in preparation for an audit, districts are effectively ‘flying blind’ for long stretches, and the eventual reconciliation process becomes a forensic exercise rather than a routine check, often surfacing the kind of discrepancies that lead directly to Audit Deficiency and Material Weakness findings.
Building reconciliation into a monthly, system-supported cadence rather than a year-end scramble is one of the highest-leverage changes a business office can make. KEV Group’s guide to strengthening school finance controls lays out a practical cadence for getting there.
School audit preparation is the set of activities a district’s business office undertakes ahead of its annual external audit to ensure financial records, supporting documentation, and internal controls are organized and defensible before the auditors arrive. This typically includes reconciling all bank and fund accounts, compiling supporting schedules for major balance sheet items, documenting internal control procedures, and resolving any known discrepancies flagged during the year.
Districts that treat audit preparation as a once-a-year sprint tend to fare worse than those that treat it as the natural output of well-run monthly processes. When reconciliation, activity fund oversight, and purchasing controls operate consistently throughout the year, as discussed under Reconciliation, audit preparation becomes a matter of assembling already-current documentation rather than reconstructing months of transactions retroactively, which is also when transcription errors and overlooked discrepancies are most likely to surface.
A structured, repeatable preparation process is the single biggest lever a business office has for avoiding findings altogether. KEV Group’s K-12 audit preparation checklist gives finance teams a month-by-month framework, and the related piece on why K-12 school districts fail audits explains what happens when that preparation is skipped.
School cash management refers to the systems and processes a district uses to collect, track, deposit, and reconcile money coming in from students, parents, and the community, spanning everything from cafeteria payments and field trip fees to activity fund dues and fundraiser proceeds. It sits at the intersection of customer-facing payment collection and the internal controls needed to keep that money properly accounted for.
Cash management has historically been a manual, paper-heavy function in K-12, with money moving through envelopes, hand-written receipts, and end-of-day cash counts across dozens or hundreds of individual school sites. That fragmentation is exactly what makes cash management a recurring source of audit findings: with money entering the system through so many different points, maintaining consistent controls and timely reconciliation across every school becomes a significant operational burden for a central business office.
Modern school cash management increasingly means shifting collection points toward digital, centrally visible payment systems rather than site-by-site manual processes. KEV Group’s overview of payment terms and processing and its guide to online payments for schools cover how districts consolidate cash management without losing site-level flexibility.
A single audit is a comprehensive, organization-wide audit required of any school district that spends at or above a certain amount in federal funds during a fiscal year, as defined by the Uniform Guidance (2 CFR 200). This number was recently revised up from $750,000 to $1,000,000 and may change in the future. Rather than a separate audit for each federal grant, the single audit combines the district’s standard financial statement audit with a compliance audit covering all of its federal award programs in one coordinated engagement.
The compliance testing in a single audit is more granular than a typical financial statement audit, since auditors test the district’s adherence to specific requirements attached to each federal program, such as allowable costs, eligibility determinations, and procurement rules, in addition to the accuracy of the underlying numbers. Districts with significant Title I, IDEA, or Child Nutrition funding are especially likely to fall under single audit requirements, and findings here can affect a district’s continued eligibility for that funding, not just its audit opinion.
Because single audits test compliance program-by-program, documentation and fund segregation matter even more than in a standard audit. KEV Group’s audit preparation checklist and its analysis of why K-12 school districts fail audits both address the federal compliance elements that single audits specifically probe.
SIS integration refers to the connection between a district’s Student Information System, the platform that holds enrollment, scheduling, and demographic data, and its other operational systems, most importantly its finance, payment, and fund accounting platforms. A well-built integration means a student’s fee obligations, enrollment status, and household information flow automatically between systems rather than being manually entered and maintained in multiple places.
Without SIS integration, business office and school staff end up maintaining duplicate student records across systems, which creates the kind of data entry burden and inconsistency that leads to billing errors, missed fee collections, and reconciliation headaches when a family’s information changes mid-year. As districts add more specialized systems like cashless payments, activity fund tracking, and facilities scheduling, the absence of integrations multiplies risk, since each new system becomes another place student data can drift out of sync.
Evaluating SIS integration depth, not just whether it exists, has become a standard part of how districts assess new finance software. KEV Group’s integrations page details how its platform connects with the SIS systems most commonly used across K-12 districts.
A student activity fund is a specific type of fund, discussed more broadly under Activity Fund, that holds money generated by and for student groups, clubs, and organizations, such as class accounts, athletic booster proceeds, field trip expenses, yearbook sales, etc. These funds are usually held in trust by the district on behalf of students rather than treated as district revenue, which shapes both how they’re accounted for and who has authority to approve spending from them.
Governance of student activity funds sits in an awkward middle ground: the money isn’t the district’s general operating revenue, but the district is still legally and fiscally responsible for how it’s handled, which means the same internal control expectations apply even though collection often happens through teachers and club advisors rather than trained business office staff. This is precisely the gap auditors probe when they test activity fund controls, and it’s why a written activity fund policy, standardized deposit forms, and advisor training are considered baseline requirements rather than optional extras.
KEV Group’s guide to student activity funds and its companion resource on activity fund best practices outline the specific policies and system controls districts use to keep student activity funds compliant year-round.
Trial Balance
A trial balance is a report listing every account in a district’s general ledger along with its ending debit or credit balance, used to confirm that total debits equal total credits before financial statements are prepared. It is a mechanical checkpoint rather than a polished financial report, and it is one of the first documents an auditor requests at the start of fieldwork.
If a trial balance doesn’t balance, it signals a posting error somewhere in the ledger that needs to be tracked down before any further reporting can proceed, which is why bookkeepers pull and review trial balances regularly throughout the year rather than
waiting until year-end close. A trial balance that stays in balance month over month, with account balances that make intuitive sense relative to prior periods, is one of the simplest early indicators that the underlying books are being maintained correctly.
Running and reviewing a trial balance as a routine monthly step, rather than only at year-end, catches ledger errors while they’re still small and easy to fix. KEV Group’s guidance on strengthening school finance controls covers where this kind of routine review fits into a broader monthly close process.
Unrestricted Funds
Unrestricted funds are dollars a school district can use for any legitimate public purpose at its discretion, without being tied to a specific program, grant, or donor stipulation, as opposed to restricted funds, which come with legal or contractual limits on how they can be spent, as is typical of federal grants or many activity fund contributions.
The size of a district’s unrestricted fund balance, usually measured as a percentage of annual operating expenditures, is one of the most closely watched indicators of financial health by boards, credit rating agencies, and state oversight bodies. Too small an unrestricted balance leaves a district exposed to cash flow gaps or unexpected costs with no flexibility to respond, while state guidelines and board policy often set minimum and sometimes maximum thresholds for how large this balance should be relative to spending.
Correctly distinguishing unrestricted from restricted funds is a core function of the fund accounting structure discussed under Fund Accounting, and getting it wrong is a common source of compliance findings. KEV Group’s solution overview covers how its platform maintains that separation automatically at the transaction level.
Vendor risk management is the process a school district follows to evaluate and monitor the financial, operational, and data-security risk posed by outside companies it contracts with, including software providers, payment processors, and other service vendors. In K-12, this has become especially relevant for finance and IT software vendors, since these systems typically hold sensitive student and financial data and connect directly into a district’s core operations.
For a district’s business office, vendor risk management usually shows up in the form of due diligence questions during procurement: What security certifications does the vendor hold? How is student and financial data encrypted and stored? What happens in the event of a data breach or extended outage? Districts increasingly build these questions into RFPs for finance and payment platforms specifically, since a vendor’s data handling practices become the district’s own compliance exposure once the contract is signed.
A vendor’s willingness to be transparent about its own security posture is itself a signal worth weighing during evaluation. KEV Group’s security page details the certifications, data protection practices, and compliance standards it maintains as a vendor handling district financial and student data.
A W-9 is an IRS form a school district collects from any vendor, contractor, or individual it pays for services, capturing that payee’s legal name, business type, and taxpayer identification number. The district keeps the completed W-9 on file rather than filing it with the IRS, and uses the information on it to prepare Form 1099 filings at year-end for any payee that meets the reporting threshold.
For a school bookkeeper, the practical rule is simple but easy to overlook under time pressure: collect a signed W-9 before issuing the first payment to a new vendor, not after. Chasing down a W-9 from a vendor who has already been paid, sometimes months or years earlier, is a common and avoidable year-end scramble that can also expose the district to IRS backup withholding penalties if the vendor never provides a valid taxpayer ID.
Building W-9 collection into new vendor setup, so a payment simply cannot be processed until the form is on file, removes this risk entirely rather than relying on staff to remember it case by case. Districts that route new vendor onboarding through their purchasing and finance system, rather than an email-based approval process, typically have far fewer year-end 1099 headaches.
XBRL, or eXtensible Business Reporting Language, is a standardized, machine-readable format for tagging financial data so it can be automatically read, compared, and analyzed by software rather than requiring manual re-entry from a printed or PDF report. It was developed primarily for corporate and regulatory financial reporting, most notably SEC filings in the private sector.
K-12 school districts do not currently file financial statements in XBRL format the way public companies do, but the underlying concept (structured, standardized financial data that different systems can read and exchange automatically) is directly relevant to how modern district finance software is built. State education finance reporting systems increasingly require data submitted in standardized digital formats, and the same principle that drives XBRL adoption in the corporate world, reducing manual re-entry and formatting errors, is why integrated fund accounting and reporting systems matter for districts.
Whether or not a specific reporting standard like XBRL applies, the broader goal, financial data that flows between systems without manual re-keying, is central to reducing reporting errors. KEV Group’s integrations page covers how its platform exchanges data with other district systems rather than requiring manual exports and re-entry.
Year-end close, sometimes called rollover in K-12 finance systems, is the process of finalizing all financial transactions for a fiscal year, reconciling every account, posting any remaining adjusting entries, and formally closing the books before opening a new fiscal year in the system. It is the point at which activity fund balances, budget carryforwards, and encumbrances get resolved and transferred into the new year’s records.
Year-end close is typically the single busiest period for a district’s business office and school-level bookkeepers alike, since every outstanding reconciliation, every unresolved purchase order, and every activity fund discrepancy must be cleared before the close can be finalized. Districts that maintain clean monthly reconciliations throughout the year, rather than deferring cleanup to year-end, experience a materially shorter and less stressful close, since most of the heavy lifting has already happened incrementally.
Automating the mechanical parts of rollover, carrying forward budgets, encumbrances, and activity fund balances without manual re-entry, significantly shortens close timelines. KEV Group’s year-end rollover automation guide walks through how that process works inside its SchoolCash platform.
Zero-based budgeting is a budgeting approach in which every expense must be justified and built up from zero each new budget cycle, rather than starting from the prior year’s budget and adjusting incrementally up or down. In a district context, this means every department or program has to make the case for its full requested spending each year, instead of last year’s line item simply being carried forward with a percentage increase.
The appeal of zero-based budgeting for school districts is that it forces a periodic re-justification of spending that incremental budgeting can let quietly persist for years, such as a program or contract that has continued out of habit long after its original need diminished. The tradeoff is that a full zero-based process is significantly more time-intensive for a business office and program leaders to execute than incremental budgeting, which is why many districts apply zero-based principles selectively, to specific departments or budget categories on a rotating basis, rather than to the entire budget every single year.
Whichever budgeting philosophy a district uses, having granular, accurate historical spending data by line item and program is what makes a zero-based review actually feasible. KEV Group’s school finance buyer’s guide covers the reporting granularity finance teams need to support this kind of budget review.